By Gregory A. Thyberg, Jr., Director of Legal Affairs
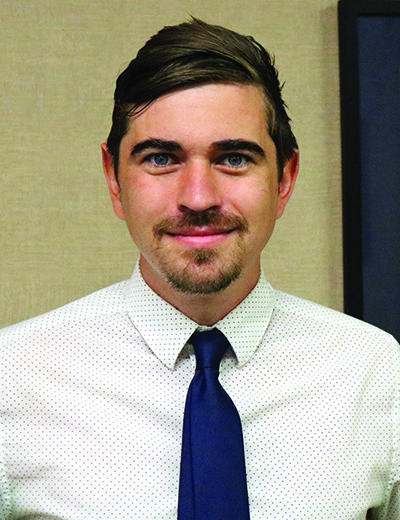
Allow me to introduce myself. I am Gregory A. Thyberg, Jr., the new Director of Legal Affairs for the Howard Jarvis Taxpayers Association.
I look forward to continuing HJTA’s work defending taxpayers and the protections of Propositions 13 and 218.
As readers of Taxing Times know, the rights of taxpayers can be won or lost in court. Did voters approve the tax being collected? Are fees based on the cost of service? When voters repeal a charge, must government respect their decision?
Those questions are at the center of most of HJTA’s cases.
In fact, we just won a great victory in Glendale.
How would you react if you voted to tax telephone and telecommunications services, only to be told years later that you had also approved a tax on Hulu, ESPN+, and Disney+?
In Hulu, LLC, et al. v. City of Glendale, the City attempted to apply its voter-approved Communications Users Tax to subscription streaming services and sought approximately $852,000 in back taxes, interest, and penalties dating back to 2019.
The critical question was simple: Did Glendale voters actually approve this tax?
While the case was pending, a Court of Appeal upheld a similar tax imposed by the City of Santa Barbara. Glendale relied on that decision. That is where HJTA stepped in.
HJTA filed an amicus curiae, or friend of the court, brief focused on Proposition 218’s voter approval requirement. We argued that the Santa Barbara case did not control because Glendale voters had been shown different ballot materials.
Those materials focused on telephone and telecommunications services. They did not adequately inform voters that the tax would apply to subscription streaming. In fact, the City’s own later budget materials stated that services such as Netflix and Hulu were not being taxed.
HJTA urged the Court to focus on what Glendale voters had actually been told and approved. A government should not be able to ask voters one question at the ballot box and later claim that the answer authorized something materially different.
On July 7, 2026, the trial court agreed with the central position advanced in HJTA’s brief. The Court held that Glendale voters had not been adequately informed that the tax would apply to present or future streaming services. The City therefore could not impose the tax without obtaining new voter approval.
HJTA’s involvement helped put the decisive issue before the Court: not simply whether streaming services could fit within the language of a communications tax, but whether Glendale voters had actually approved taxing them.
The ruling matters beyond streaming. Technology changes and new services emerge, but technological change cannot become an excuse to bypass the voters. When the law requires voter approval, voters must be told what they are being asked to approve.
The Glendale case remains open because the ruling may be subject to further proceedings or appeal. But the decision is already an important affirmation of Proposition 218’s voter approval protections.
Another important Proposition 218 case is before the California Supreme Court, involving the sometimes complicated issue of water rates.
In Dreher v. City of Los Angeles Department of Water and Power, Los Angeles uses tiered water rates that assign different costs based partly on water budgets tied to parcel size and temperature zone. Two customers using the same amount of water may therefore pay different rates.
HJTA filed an amicus brief on July 1 arguing that these water budget breakpoints are based on policy judgments about reasonable use, rather than the proportional cost of service required by Proposition 218. The case is now fully briefed.
A third case asks what happens when voters repeal assessments, but the government continues trying to collect them.
In 2024, El Dorado Hills voters approved Measures Q, R, and S by more than a two-thirds majority, repealing certain landscaping and lighting assessments. Despite those results, the District sought to continue placing the assessments on the tax roll and sued when the County Auditor Controller refused.
HJTA and a local citizens group sought to intervene, but the Court denied intervention. HJTA then learned that an existing Real Party in Interest was unrepresented. HJTF agreed to represent that party and is now counsel of record.
The common thread in all three of these cases is that HJTA will fight to ensure the government will follow the rules set in Propositions 13 and 218.
These cases involve different subjects, but they share one principle: Government must follow the rules.
As HJTA’s new Director of Legal Affairs, I look forward to helping defend that principle in court.